AI for Accountants: Tools, Use Cases and Risks in 2026
Posted On: August 1, 2026
Last updated: September 2026 · Written by Clara Miller, Content Marketing Specialist at AI Workforce · Reviewed by Rodi Taze, Co-Founder of AI Workforce
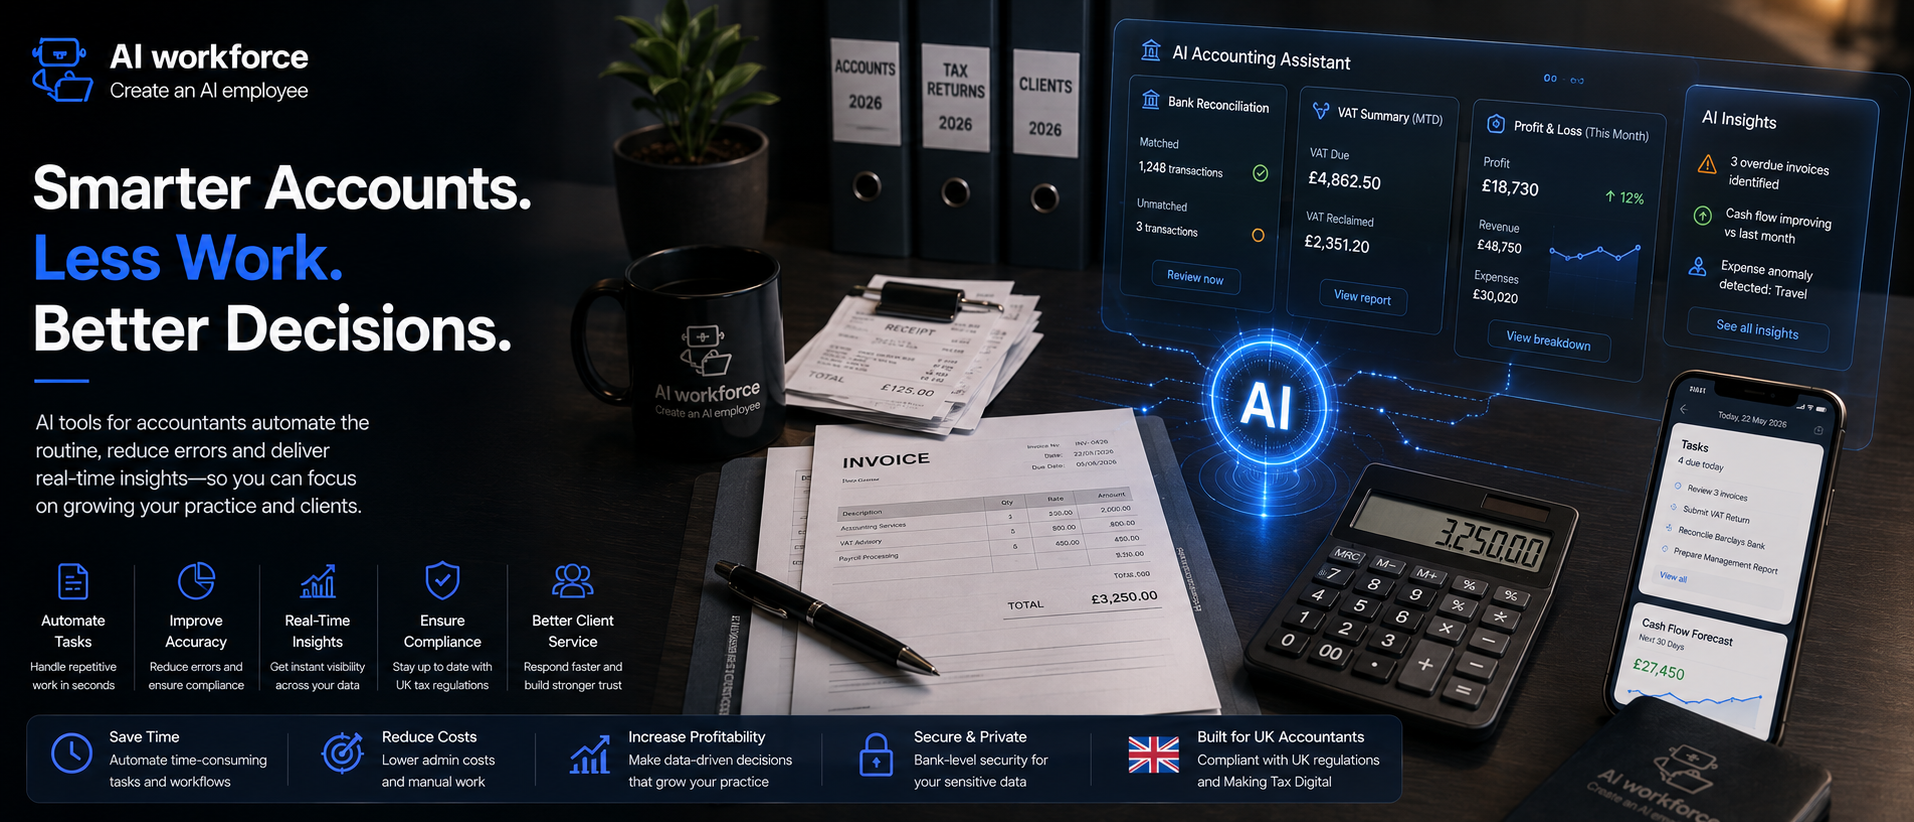
AI is already part of daily work for many accounting and finance teams: extracting data from a scanned receipt, flagging an unusual transaction, drafting a first-pass client email, summarising a long technical standard. Practical tools now exist to help accountants and bookkeepers work faster on the repetitive parts of the job. The question worth asking is no longer simply "can accountants use AI?" It is which tasks AI should handle, which tools are actually appropriate for accounting work, and where professional judgement has to stay with a qualified person.
Quick Answer
AI can help accountants reduce repetitive work across document processing, bookkeeping, reporting, client administration, research and practice management. Useful tools range from accounting platforms such as Xero and practice-management systems such as Karbon, through document-capture tools such as Dext and accounts-payable automation such as ApprovalMax, to general-purpose AI assistants such as Microsoft Copilot and ChatGPT. The strongest use cases automate repetitive preparation and first-pass analysis, while tax positions, audit conclusions, financial sign-off and consequential client advice stay with a qualified person.
At a Glance
What it is: AI software used to automate, analyse or assist accounting, bookkeeping and practice-management work
Best suited to: firms where document processing, client administration, reconciliation, reporting or routine communication consumes significant staff time
Strongest early use cases: document extraction, bookkeeping support, reminders, meeting summaries, first-draft correspondence and anomaly flagging
What should remain human-led: tax positions, audit conclusions, financial sign-off, material accounting judgements and consequential client advice
Biggest risk: treating an AI-generated answer or classification as authoritative without checking the underlying evidence
UK consideration: client confidentiality, UK GDPR, professional obligations and authoritative HMRC or accounting-body guidance still apply when AI is used
What's Covered
Best AI Tools for Accountants in 2026
These five tools represent different accounting workflows rather than seven variations on the same chatbot. Each was checked against current official vendor documentation; this is a desk-based review of public material, not hands-on testing of every feature.
Swipe to see all columns →
Tool | Best for | What it helps automate | Main limitation |
|---|---|---|---|
Xero | Cloud accounting for small and mid-sized clients | Bank reconciliation, data entry and payment chasing via its JAX AI agent | AI insights depend on connected data quality; does not replace accountant review of the accounts |
Karbon | Practice management for accounting firms | Email summarising, task assignment suggestions, time-entry correction and firm-wide status insights via Kai | Kai's agentic features are still in early access and work only within Karbon's own data |
Dext | Receipt and invoice data capture | Extracting supplier, date, amount and line-item data from receipts, invoices and statements | Vendor-claimed accuracy is high but not absolute; extracted data still needs review before publishing, especially for unusual suppliers |
ApprovalMax | Accounts payable approval workflows | Invoice data capture, duplicate and anomaly detection, approval routing and fraud-pattern flagging | Works best on clean, centralised AP data; performs poorly where invoice handling is fragmented across spreadsheets and email |
Microsoft Copilot / ChatGPT | General drafting, research and explanation | First-draft correspondence, summarising technical material, structuring research questions, meeting notes | Not an authoritative source for tax or accounting positions; outputs need checking against GOV.UK, HMRC or professional guidance |
Xero
Best for: firms and small businesses already running cloud accounting who want AI layered directly into day-to-day bookkeeping.
What AI genuinely helps with: Xero's JAX agent automates routine work such as bank reconciliation, data entry and chasing payment, and surfaces financial insights drawn from connected data. Xero states JAX uses an internal "Assure" control system intended to reduce inaccurate outputs.
What still needs an accountant: reviewing the accounts JAX has touched, confirming reconciliations that involve judgement, and interpreting any insight before it informs client advice.
Main limitation: the quality of JAX's output depends on the quality of connected data, and Xero itself does not present it as a substitute for the accountant's own review.
Official source: Xero JAX media release.
Karbon
Best for: practices that want client work, deadlines and team workflow centralised in one system.
What AI genuinely helps with: Kai, Karbon's AI coworker, summarises email threads, drafts brand-aligned replies, suggests task assignments based on work history, corrects missed time entries and generates executive summaries on client status and profitability.
What still needs an accountant: approving client-facing communication, checking task assignments make sense, and treating summaries as a starting point rather than a finished judgement.
Main limitation: Kai's more autonomous, agentic features remain in early access, and it only works with data already inside Karbon, not external sources.
Official source: Karbon AI feature page.
Dext
Best for: practices and bookkeepers handling high volumes of receipts, invoices and supplier statements.
What AI genuinely helps with: Dext extracts supplier, date, amount and category data from receipts and invoices, flags duplicates, and syncs the result into Xero, QuickBooks and other accounting platforms, either automatically or with manual review before publishing.
What still needs an accountant: reviewing extractions for unusual suppliers or documents, and deciding which suppliers are safe to auto-publish versus which need manual sign-off.
Main limitation: Dext advertises very high extraction accuracy, but that still implies a non-zero error rate, and setup work is needed before features like automatic line-item splitting are reliable.
Official source: Dext bookkeeping automation page.
ApprovalMax
Best for: firms and finance teams that want structured, auditable approval workflows around accounts payable.
What AI genuinely helps with: capturing invoice data regardless of format, catching duplicate invoices and mismatched amounts, routing invoices to the right approver over time, and flagging fraud indicators such as a supplier bank account changing shortly before a large payment.
What still needs an accountant: resolving flagged exceptions, confirming unusual approvals, and maintaining clean master data and documented approval rules, since AI performance depends on both.
Main limitation: ApprovalMax itself is explicit that AI "is a lens, not a remedy" — it exposes problems in an existing AP process rather than fixing a fragmented or undocumented one.
Official source: ApprovalMax on AI in accounts payable.
Microsoft Copilot / ChatGPT
Best for: general drafting, research structuring and explaining unfamiliar material, used alongside accounting-specific tools rather than instead of them.
What AI genuinely helps with: drafting routine client correspondence, summarising a long technical standard into plain English, preparing meeting notes, and structuring a research question before you go looking for the authoritative answer.
What still needs an accountant: verifying any tax, accounting or regulatory content against GOV.UK, HMRC or professional-body guidance, and reviewing anything before it reaches a client.
Main limitation: general-purpose models are not authoritative sources on tax or accounting positions, and tax information changes; treat their output as a first draft, not a citation.
What Can Accountants Actually Use AI For?
Practical use cases fall into a handful of categories. In each, AI produces a first-pass output; the accountant decides whether it is right.
Bookkeeping support: AI can prepare transaction categorisation suggestions and flag likely miscodes; the accountant confirms anything material or unusual
Invoice and receipt processing: AI can extract supplier, date, amount and VAT fields from a document; the accountant checks extractions on unfamiliar suppliers or poor-quality scans
Reconciliations: AI can suggest matches and flag exceptions across bank and ledger data; the accountant reviews ambiguous matches and anything with weak supporting evidence
Financial reporting preparation: AI can aggregate data, flag variances and draft a first-pass management commentary; the accountant checks the numbers and owns the final commentary
Anomaly detection: AI can surface one unusual transaction among thousands; the accountant decides whether it actually matters
Audit support: AI can help analyse a larger transaction population and organise evidence; the auditor determines sufficiency of evidence and the audit conclusion
Client email drafting: AI can draft document requests, reminders and routine status updates; a person reviews anything involving tax advice, complaints or sensitive matters
Meeting notes: AI can transcribe and summarise a client call; the accountant checks anything that will inform advice or be quoted back to the client
Document summarisation and research: AI can summarise a technical standard or structure a research question; the accountant verifies the answer against authoritative material
Practice management: AI can suggest task assignments, correct time entries and generate status summaries; a person still owns staffing and client-facing decisions
Reminders and workflow coordination: AI can send routine deadline and document-chasing reminders with limited oversight needed
Companies House monitoring: AI-assisted tools can flag newly incorporated companies or changes to a client's public filings for administrative awareness, within the limits of what the public register actually contains
What Is AI in Accounting and How Does It Actually Work?
Not every feature marketed as "AI" is the same kind of technology, and the distinction matters when judging how much to trust a given output.
Rules-based automation: fixed triggers and deterministic workflows — if a condition is met, a defined action happens. Reliable, but only as good as the rules someone wrote
Machine learning: pattern recognition trained on historical data, used for categorisation, anomaly detection and prediction. Improves with more relevant data, but can carry forward the biases in that data
Generative AI: large language models that draft, summarise, explain and hold a natural-language conversation. Fluent and fast, but not inherently accurate or authoritative
AI agents: multi-step workflows that combine the above and act within defined permissions, such as Xero's JAX or Karbon's Kai. More capable, but also carry more risk if permissions are set too broadly
AI tool selection matters more than most firms expect: tools built specifically for accounting handle terminology, formatting and compliance requirements that a general-purpose assistant was not designed for. Accountants tend to get the most value from AI applied to one specific, well-defined task rather than everything at once.
Can AI Actually Take Over an Accountant's Job?
No, not for the parts of the job that require professional judgement, accountability, client relationships and interpreting a genuinely ambiguous situation. AI changes the mix of work rather than removing the accountant from it. It can meaningfully reduce manual data entry, repetitive document handling, routine drafting and first-pass research. It should not independently own tax positions, audit conclusions, financial sign-off, material accounting judgements or consequential client advice.
Responsible AI deployment means being upfront with clients and staff about exactly where a tool sits in a given process. Firms that blur that line, or let a tool's output stand in for a review that should have happened, tend to run into trouble the first time it gets something wrong on a matter that actually mattered.
How Are Accounting Firms Actually Using AI?
AI adoption is increasing across the accounting profession, although usage varies considerably by firm size, technology stack and type of work, and firm-wide adoption statistics should be treated cautiously given how quickly tool capability and usage patterns are still changing. Larger firms can generally absorb the cost of piloting several tools before committing, while a smaller practice usually needs to select and commit earlier. Bodies including ICAEW and ACCA have both published ongoing commentary on AI adoption in the profession; treat any specific adoption percentage you encounter as a snapshot from a particular survey rather than a fixed industry figure, and check the original source before citing it.
Investment in AI increasingly shows up as a standard line in the annual technology budget rather than a one-off experiment, but the shape of that investment differs a great deal between a sole practitioner and a multi-office firm.
What Can AI Do for Financial Reporting?
Financial reporting benefits from automating the repetitive parts: pulling figures from source systems, aggregating and formatting them consistently, flagging a variance or a number that looks wrong before it reaches a partner for review. Useful tasks include data aggregation, reconciliation support, variance flagging, first-draft management commentary, anomaly detection and formatting. AI does not sign off financial statements; a qualified person reviews the underlying data and takes responsibility for what is published.
What Can AI Do for Audit?
Audit is a professional, evidence-sensitive workflow, and AI's role there is narrower than in bookkeeping. Useful support includes analysing a fuller transaction population rather than a sample, flagging anomalies, assisting document review, surfacing risk indicators worth investigating, and helping organise evidence. AI can identify something worth looking at; it does not decide whether it matters, what evidence is sufficient, or what the audit conclusion should be. Those remain the auditor's responsibility, and any specific claim about a tool "predicting audit risk" should be checked against what the vendor actually documents rather than taken as a given.
How Does AI Help With Manual Processing and Bookkeeping?
Manual data entry used to mean hours of typing figures from a paper source into a ledger, line by line. Document-capture tools now extract the supplier, amount, date and, where supported, VAT information straight from a scanned receipt or invoice, then feed it into the accounting system. This works well for standard documents and improves as the underlying model sees more real examples, but extraction accuracy is not infallible: an unfamiliar supplier, a handwritten receipt or a poor scan can still produce a wrong field, so extracted data should still be checked where it is material, particularly before auto-publishing to the ledger.
How Does AI Help With Reconciliations?
AI and automation can suggest matches between bank and ledger data, flag exceptions, identify unusual transactions and prioritise unmatched items so a person's attention goes where it is needed most. The accountant or bookkeeper should still review ambiguous matches, unusual transactions, material adjustments and anything with weak supporting evidence, rather than accepting every suggested match automatically.
Generative AI for Accountants
Generative AI is useful for drafting client correspondence, summarising technical material, explaining unfamiliar terminology, preparing meeting notes, producing a first-draft management commentary, structuring research questions and building checklists. A specific, evidence-grounded prompt reliably outperforms a vague one: asking for "a plain-English summary of this specific HMRC guidance page for a client with these facts" gets a more useful answer than asking a general question about the topic.
Do not treat a general AI model as an authoritative source for tax or accounting advice. Where AI is used for tax research, explanations, HMRC processes, deadlines, allowances, rates or tax treatment, check the final answer against current authoritative material: GOV.UK, HMRC guidance, or relevant professional-body guidance. Tax rules and figures change, and a fluent-sounding answer is not the same as a current one.
What Accounting Work Should Stay Human-Led?
The message here is not that AI is unsafe. It is that the more consequential and judgement-dependent a task is, the stronger the human review requirement needs to be. Work that should stay human-led includes tax positions, audit opinions and conclusions, financial-statement sign-off, material accounting judgements, complex client advice, ethical judgements, disputed transactions, consequential regulatory interpretations, and final approval of any externally relied-upon financial information.
What Should Accountants Automate, Review or Keep Human-Led?
These boundaries are illustrative. The right line for your practice depends on materiality, firm policy, professional obligations, client circumstances and the specific risk involved.
Swipe to see all columns →
Lower risk to automate heavily | AI prepares, accountant verifies | Human-led |
|---|---|---|
Meeting transcription | Draft client emails | Tax positions |
Routine reminders | Reconciliation suggestions | Audit conclusions |
Document classification | Management commentary | Financial sign-off |
Data extraction | Anomaly explanations | Material judgements |
Workflow notifications | Research summaries | Consequential client advice |
Basic information gathering | Bookkeeping categorisation suggestions | Regulatory interpretations |
The AI Workforce Accounting Implementation Model
This is an AI Workforce framework, not an industry standard. It gives a practice a simple way to introduce AI into one workflow without losing oversight.
Identify → Connect → Automate → Verify → Measure
Identify: choose one repetitive, measurable accounting workflow, not the whole practice at once
Connect: provide the minimum approved systems and data the workflow genuinely needs
Automate: let the AI or software handle the repeatable preparation work
Verify: a named person reviews material outputs and exceptions before they go further
Measure: track time saved, correction rate, exceptions and quality, not just volume produced
How Should Accountants Actually Start Using AI?
Start small: one repetitive task, properly measured, before anything scales further. Firm-wide deployment on day one is the most common way this goes wrong.
Week 1: select one repetitive workflow and establish a baseline for time and error rate
Week 2: run the AI tool in assist or recommend mode, with a person checking every output
Week 3: measure correction rate and time saved against the baseline
Week 4: expand only the low-risk elements that have proven reliable, and keep verifying anything judgement-dependent
Practical AI support built around a specific job tends to outperform a broad platform trying to do everything at once, and checking a tool's actual functionality against your real workflow beats trusting a polished demo. Learn how to use a new tool properly before rolling it out to a whole team, and tell clients what has changed: a client who does not know a draft came from a tool is more likely to be surprised later than reassured now.
What Should Firms Measure?
Processing time per invoice or document
Reconciliation time
Time spent on client administration
Time spent preparing management reports
Correction rate
Exception rate
Percentage of AI suggestions accepted without change
Turnaround time
Hours returned to advisory or client-facing work
Number of material errors caught during review
Number of AI outputs generated is not a useful success metric on its own: a tool that drafts more of everything without a corresponding drop in correction rate or time spent has not actually saved the practice anything.
Client Communication
AI can help draft document requests, appointment reminders, routine status updates, meeting follow-ups and explanations of straightforward processes. A person should review anything involving tax advice, complaints, sensitive financial matters, disputes, unusual client circumstances or a material recommendation before it goes out under the practice's name.
Client Confidentiality
Accountants routinely handle highly sensitive client information, and that does not stop applying once a task moves through an AI tool. Before putting client information into any AI service, check what data is actually being uploaded, whether personal data is genuinely necessary for the task, whether it can be minimised or anonymised first, retention periods, storage location, the vendor's subprocessors, whether submitted content is used to train the provider's models, access controls, deletion rights, and the contractual terms that apply. Do not casually paste full tax returns, payroll data, bank details, client correspondence or identity documents into a general AI service without appropriate controls in place first.
UK GDPR
This is general information rather than legal advice.
Client data processed through an AI tool is still subject to UK GDPR. Before adopting a tool, consider the lawful basis for processing, purpose limitation, data minimisation, accuracy, security, retention, transparency to the client, and, where relevant, which party is the controller and which is the processor. Check whether the vendor transfers data internationally, who can access it within your practice, and whether your use of the tool is genuinely auditable. A product is not automatically "GDPR compliant" simply because it offers security features; compliance depends on how it is configured and used, not only on the vendor's own controls.
Companies House Data for Accounting Practices
Companies House's public register is useful for practical administrative tasks: checking a client or prospect's company status, incorporation date, registered office, SIC codes, and director or public filing history, and monitoring newly incorporated companies or changes relevant to client onboarding or prospecting. It is genuinely useful, but it is not a complete solution on its own: Companies House public data does not include private contact information, does not give permission to market to a named individual, and does not provide complete financial intelligence about a business. Treat it as one input into client administration and prospecting, not a shortcut around consent or verification requirements elsewhere.
Considering AI Beyond the Accounting Software Itself?
AI Workforce builds practical automation around client administration and communication, including Companies House-based company monitoring and AI receptionist support for client calls, so your practice's own systems do the routine work while your team keeps ownership of the judgement calls.
Related Guides
Frequently Asked Questions
What is the best AI tool for accountants?
There is no single best tool. Xero's JAX suits practices already on Xero wanting AI built into bookkeeping, Karbon's Kai suits practices that centralise work there, Dext suits high-volume receipt and invoice capture, ApprovalMax suits structured accounts-payable approval workflows, and Microsoft Copilot or ChatGPT suit general drafting and research alongside accounting-specific tools.
Can AI replace accountants?
No. AI can reduce manual data entry, repetitive document handling and first-pass drafting, but tax positions, audit conclusions, financial sign-off and material accounting judgements need to stay with a qualified person.
Is AI accounting software accurate?
Modern document-extraction and categorisation tools are accurate for standard documents but not infallible. Unusual suppliers, poor scans or edge cases can still produce errors, so extracted or categorised data should be reviewed where it is material.
Can I use ChatGPT for tax advice?
Not as an authoritative source. General AI models are useful for drafting and explaining, but any tax position, deadline, allowance or rate should be checked against GOV.UK, HMRC guidance or relevant professional-body material before it is relied on.
Is it safe to put client data into an AI tool?
It depends on the tool and how it is configured. Check what data is being uploaded, whether it is necessary, retention and storage terms, subprocessors, whether it is used for model training, and access controls before putting sensitive client information into any AI service.
What accounting tasks should not be automated?
Tax positions, audit opinions, financial-statement sign-off, material accounting judgements, complex or consequential client advice, disputed transactions and regulatory interpretations should stay human-led, regardless of how confident an AI-generated answer looks.
How is AI used in audit?
AI can help analyse a fuller transaction population, flag anomalies, assist document review and organise evidence. The auditor still determines whether a flagged item matters, what evidence is sufficient, and the audit conclusion itself.
Does AI help with bookkeeping?
Yes. AI-assisted tools can extract data from receipts and invoices, suggest transaction categories, and flag likely miscodes or duplicates, reducing manual entry. Extracted or suggested data should still be reviewed where it is material.
How should a small accounting practice start using AI?
Start with one repetitive, measurable workflow, run the tool in assist mode with a person checking every output, measure time saved and correction rate, then expand only the parts that have proven reliable.
Is Companies House data enough for client prospecting?
It is a useful starting point for checking company status, incorporation details and filings, but it does not include private contact information or permission to market to a named individual, so it needs to sit alongside proper consent and verification steps.
Key Takeaways
AI tools handle the repetitive parts of accounting work; tax positions, audit conclusions and financial sign-off still need a qualified person
Useful tools span different workflows: accounting platforms, practice management, document capture, accounts-payable automation and general drafting assistants
AI adoption is increasing across the profession, but firm-wide adoption figures vary by source and should be checked before being cited as fact
Financial reporting, audit support and everyday document processing are where the earliest, clearest wins tend to show up
Generative AI works best with a specific, evidence-grounded prompt, and should never be treated as an authoritative source on tax or accounting positions
Client confidentiality and UK GDPR apply in full once client data reaches an AI tool
Starting with one measured workflow beats a firm-wide rollout with no baseline
Being upfront with clients about what changed builds trust faster than staying quiet about it
This article is general information rather than legal, tax or professional advice. Named-tool features and pricing change frequently. Confirm current details directly on each provider's own documentation, and confirm tax and regulatory positions against GOV.UK, HMRC or your professional body before relying on them.
About the Author and Reviewer
Clara Miller is a Content Marketing Specialist at AI Workforce, where she researches and writes about business automation and AI adoption for UK small and medium-sized businesses, using current vendor documentation and product research.
Rodi Taze is Co-Founder of AI Workforce, with operational experience implementing AI workflows and governance controls for client businesses. This article was reviewed for product accuracy, practical value and commercial relevance.
Reviewed: September 2026